
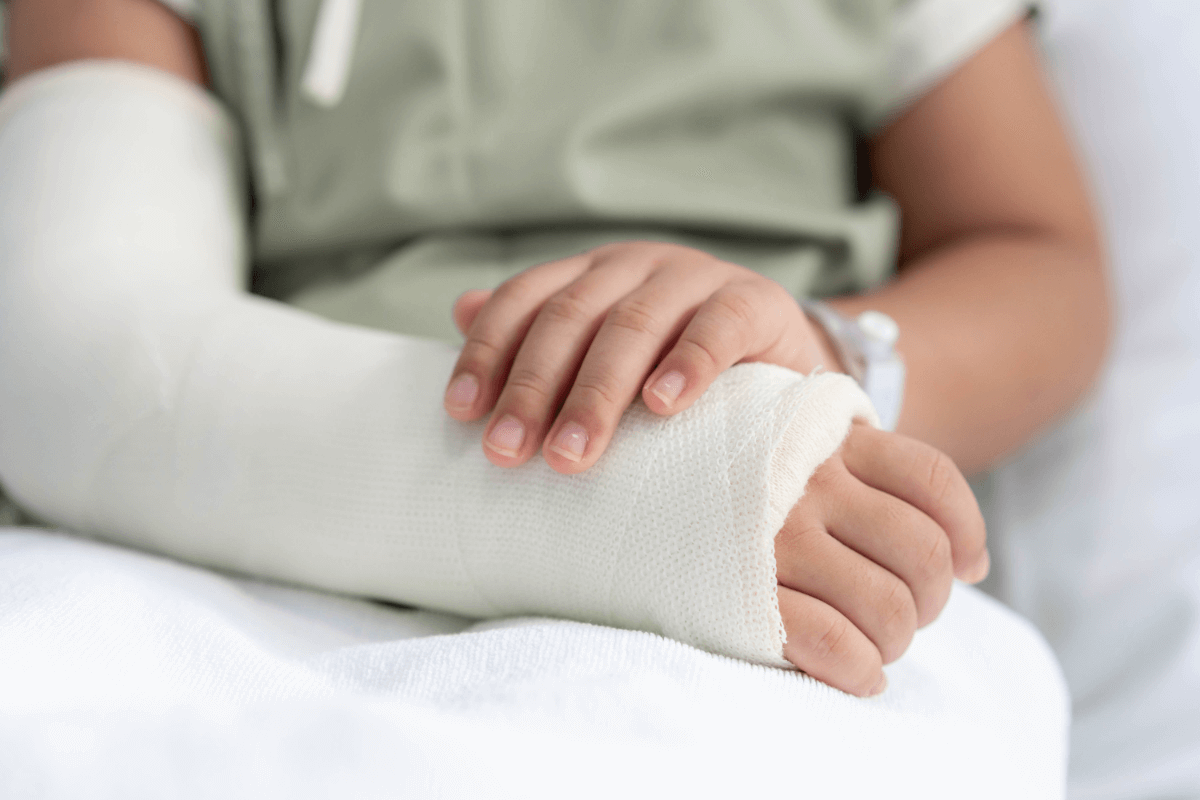
HOW MUCH COMPENSATION CAN I CLAIM FOR A PERSONAL INJURY?
It is the first question almost everyone asks, and it is the one no honest solicitor will answer with a single number on day one. Two people can break the same bone and end up with very different awards, because compensation is designed to reflect the effect the injury has had on that particular person's life and finances.
What we can do is explain exactly how the sum is built up, so you can see what will drive the value of your own claim and what evidence matters.
WHAT ARE THE TWO PARTS OF A COMPENSATION CLAIM?
1
— GENERAL DAMAGES
General damages compensate you for the injury itself — what lawyers call pain, suffering and loss of amenity (PSLA). "Loss of amenity" means the things you can no longer do, or can no longer do in the same way: your job, your sport, playing with your children, sleeping through the night.
This part of the claim cannot be evidenced with receipts. It is valued by comparing your injury and its effects against published guidance and previously decided cases.
2
— SPECIAL DAMAGES
Special damages compensate you for financial loss caused by the accident. This part is evidenced, item by item. It commonly includes:
Loss of earnings — past and, where relevant, future
Loss of pension contributions
Medical and treatment costs — physiotherapy, prescriptions, counselling, private treatment where reasonable
Travel costs — to and from medical appointments
Care and assistance — including unpaid help from family, which is claimable
Aids, equipment and adaptations
Damaged property — clothing, a phone, a bicycle, a vehicle
Additional costs — childcare, cleaning, gardening you can no longer do
In serious injury claims, special damages frequently exceed general damages by a wide margin. This is where careful evidence-gathering makes the greatest difference.
— HOW ARE GENERAL DAMAGES VALUED?
Courts and solicitors in England and Wales use the Judicial College Guidelines for the Assessment of General Damages in Personal Injury Cases. The 18th edition was published on 9 April 2026 and increased the previous figures by approximately 8.26%, reflecting movement in the Retail Prices Index to August 2025.
The Guidelines set out brackets for each type of injury, graded by severity. They are guidance rather than a tariff — a judge is not bound by them, and the introduction to the Guidelines is explicit that no two injuries are identical in their effect.
Where your injury falls within a bracket depends on factors such as:
how severe the injury was at its worst
how long symptoms lasted, or are expected to last
whether there is any permanent disability, scarring or ongoing pain
the effect on your ability to work
your age and how the injury interacts with the rest of your life
whether treatment or surgery is still needed
— WHY IS WHIPLASH COMPENSATION CALCULATED DIFFERENTLY?
If you suffered a whiplash injury in a road traffic accident in England or Wales, your general damages may not be valued using the Judicial College Guidelines at all.
The Civil Liability Act 2018 and the Whiplash Injury Regulations 2021, in force since 31 May 2021, introduced a fixed tariff for whiplash injuries lasting up to two years. Under the tariff:
the figure is set by the duration of your symptoms, in fixed bands running from "up to 3 months" through to "18 to 24 months"
there is a slightly higher figure where the whiplash is accompanied by a minor psychological injury, such as travel anxiety
your individual circumstances do not change the tariff figure
The tariff amounts were increased by approximately 15% from 31 May 2025. Which set of figures applies depends on the date of your accident.
— WHAT CAN REDUCE THE AMOUNT YOU RECEIVE
Contributory negligence. If you were partly responsible for the accident or for the extent of your injuries, your compensation is reduced by a percentage. Not wearing a seatbelt is the classic example. Being partly at fault does not stop you claiming — it reduces the award.
Failure to mitigate. You are expected to take reasonable steps to limit your losses, such as attending treatment that has been recommended.
Existing conditions. If you already had a back problem and the accident made it worse, the claim is for the worsening, not for the whole condition.
Recoverable benefits. Certain state benefits paid because of the accident are repaid to the Compensation Recovery Unit out of the settlement.
Success fee and insurance premium. Under a no win, no fee agreement, a success fee is deducted from your damages. In personal injury claims it is capped at 25% of your general damages and past financial losses — it cannot be taken from damages awarded for future losses.
— HOW THE VALUE OF THE CLAIM IS ESTABLISHED
1
Medical evidence. An independent medical expert examines you and reports on your injuries, your treatment and your prognosis. This report is the foundation of the general damages valuation. In more serious cases, several experts in different specialisms may be needed.
2
Financial evidence. Payslips, bank statements, receipts, invoices, care diaries and employer records establish what the accident has actually cost you.
3
Comparison and valuation. Your solicitor applies the Guidelines (or the tariff, where relevant) and comparable decided cases to arrive at a realistic bracket, then adds the evidenced financial losses.
4
Negotiation. Most claims settle by negotiation. Formal offers may be made under Part 36 of the Civil Procedure Rules, which carries costs consequences for whoever unreasonably refuses a reasonable offer
5
Court, if necessary. A minority of claims are decided by a judge. Even where proceedings are issued, most settle before a final hearing.
— FREQUENTLY ASKED QUESTIONS
-
There is no fixed answer. Your award will combine general damages for the injury itself, valued using the Judicial College Guidelines, with special damages for your evidenced financial losses. A realistic range can usually be given once medical evidence is available.
-
General damages compensate for pain, suffering and loss of enjoyment of life. Special damages compensate for money you have actually lost or spent because of the accident, such as earnings, treatment and travel.
-
They are the published guidance used by courts and solicitors in England and Wales to value general damages. The 18th edition was published on 9 April 2026 and increased the previous figures by around 8.26% to reflect inflation.
-
For road traffic accidents in England and Wales, whiplash lasting up to two years is compensated at a fixed tariff set by regulations, based on how long symptoms last. Other injuries and all financial losses are claimed separately, on top of the tariff figure.
-
Yes. Lost earnings are a standard part of special damages, including lost overtime, bonuses and pension contributions where they can be evidenced.
-
Usually yes. Your compensation would be reduced by the percentage you were responsible for, but a finding of partial fault does not prevent a claim.
-
Yes. Unpaid care and assistance provided by family or friends is claimable. Keeping a simple diary of the hours and tasks makes this much easier to evidence.
-
Personal injury compensation is generally not subject to income tax or capital gains tax in the UK. Interest and investment income earned on a large award afterwards may be taxable, and a substantial award can affect means-tested benefits — take advice on both.
-
It depends on how quickly liability is resolved and how long your recovery takes. A claim should not usually be settled until the medical prognosis is clear, because settling early risks undervaluing a long-term injury. Interim payments can sometimes be arranged in the meantime.
— FIND OUT WHAT YOUR CLAIM IS WORTH
0330 818 1202 — injuriesdirect@njslaw.co.uk or fill out a form