
ACCIDENT AT WORK CLAIMS
If you've been hurt at work, you're probably dealing with more than the injury itself. There's time off, lost wages, and often a real worry about what claiming will mean for your job. Your employer has a legal duty to keep you safe. If they fell short and you were injured as a result, you may be entitled to compensation.
Injuries Direct is a trading style of NJS Law, an SRA-regulated firm with a dedicated employer's liability team. We explain your options in plain English, with no confusion and no pressure.
THE SHORT ANSWER IS
You can usually claim compensation for an accident at work if your employer failed to take reasonable care for your safety and you were injured as a result. You normally have three years from the date of the accident to start a claim. The claim is paid by your employer's compulsory insurance, not by your employer personally.
WHAT IS AN ACCIDENT AT WORK CLAIM?
An accident at work claim is a claim for compensation when you are injured at work because your employer failed to take reasonable care for your safety. It is also called an employer's liability claim.
Every employer in England and Wales owes its workers a duty of care. That duty is backed up by health and safety law, including the Health and Safety at Work etc. Act 1974 and regulations covering equipment, manual handling, working at height and protective equipment. Under the Employers' Liability (Compulsory Insurance) Act 1969, most employers must also hold insurance that covers exactly this situation.
Compensation is usually made up of two parts:
General damages: for the pain, suffering and loss of amenity caused by your injury.
Special damages: for the financial losses and costs you've incurred, such as lost earnings, travel to appointments, medication, care from family members and treatment costs.
CAN I CLAIM AGAINST MY EMPLOYER?
You may be able to claim if all of the following apply:
You were injured at work, or while carrying out work duties, within the last three years.
Your employer, or someone they are responsible for, failed to take reasonable care for your safety.
That failure caused or contributed to your injury.
Many people assume they can't claim because they were partly to blame. That isn't necessarily the case. If you were partly at fault, you may still be able to claim, although your compensation may be reduced to reflect your share of responsibility. This is known as contributory negligence.
If you're not sure whether your situation qualifies, our team can give you a free, honest assessment.
WILL I LOSE MY JOB IF I CLAIM?
Worry about your job is one of the most common reasons injured workers don't claim. It's an understandable concern, and it deserves a straight answer.
Employment law protects workers who raise genuine health and safety concerns, and dismissing or disadvantaging someone for bringing a legitimate claim is likely to be unlawful. [VERIFY: employment law sign-off on this wording.] In practice, the claim is dealt with by your employer's insurer, not by your manager or colleagues. Employers are required by law to hold this insurance precisely because workplace accidents happen.
If you are treated unfairly because you claimed, tell us straight away.
WHAT SHOULD I DO AFTER AN ACCIDENT AT WORK
1
Get medical attention. Your health comes first, and medical records also document your injury.
2
Report the accident and make sure it's in the accident book. Employers with ten or more employees must keep an accident book.
3
Take photos of the scene, the hazard and your injuries if you can.
4
Get the names and contact details of anyone who saw what happened.
5
Keep a record of your time off, lost earnings and any expenses.
6
Speak to a specialist before signing anything or giving a statement to an insurer.
HOW LONG DO I HAVE TO MAKE A CLAIM?
You normally have three years from the date of the accident to start court proceedings, under the Limitation Act 1980. If you miss the deadline, you are likely to lose the right to claim, so it's best to get advice early.
There are important exceptions:
Injuries that appear later: The three years may run from the date you first knew your injury was significant and linked to your work (the "date of knowledge"). This often applies to industrial diseases.
Children: Anyone injured under 18 has until their 21st birthday. A parent or guardian can claim on their behalf before then.
Lack of mental capacity: The time limit is paused while the injured person lacks capacity to manage a claim.
Fatal accidents: Where a worker has died, the family normally has three years from the date of death.
HOW MUCH COMPENSATION CAN I RECEIVE?
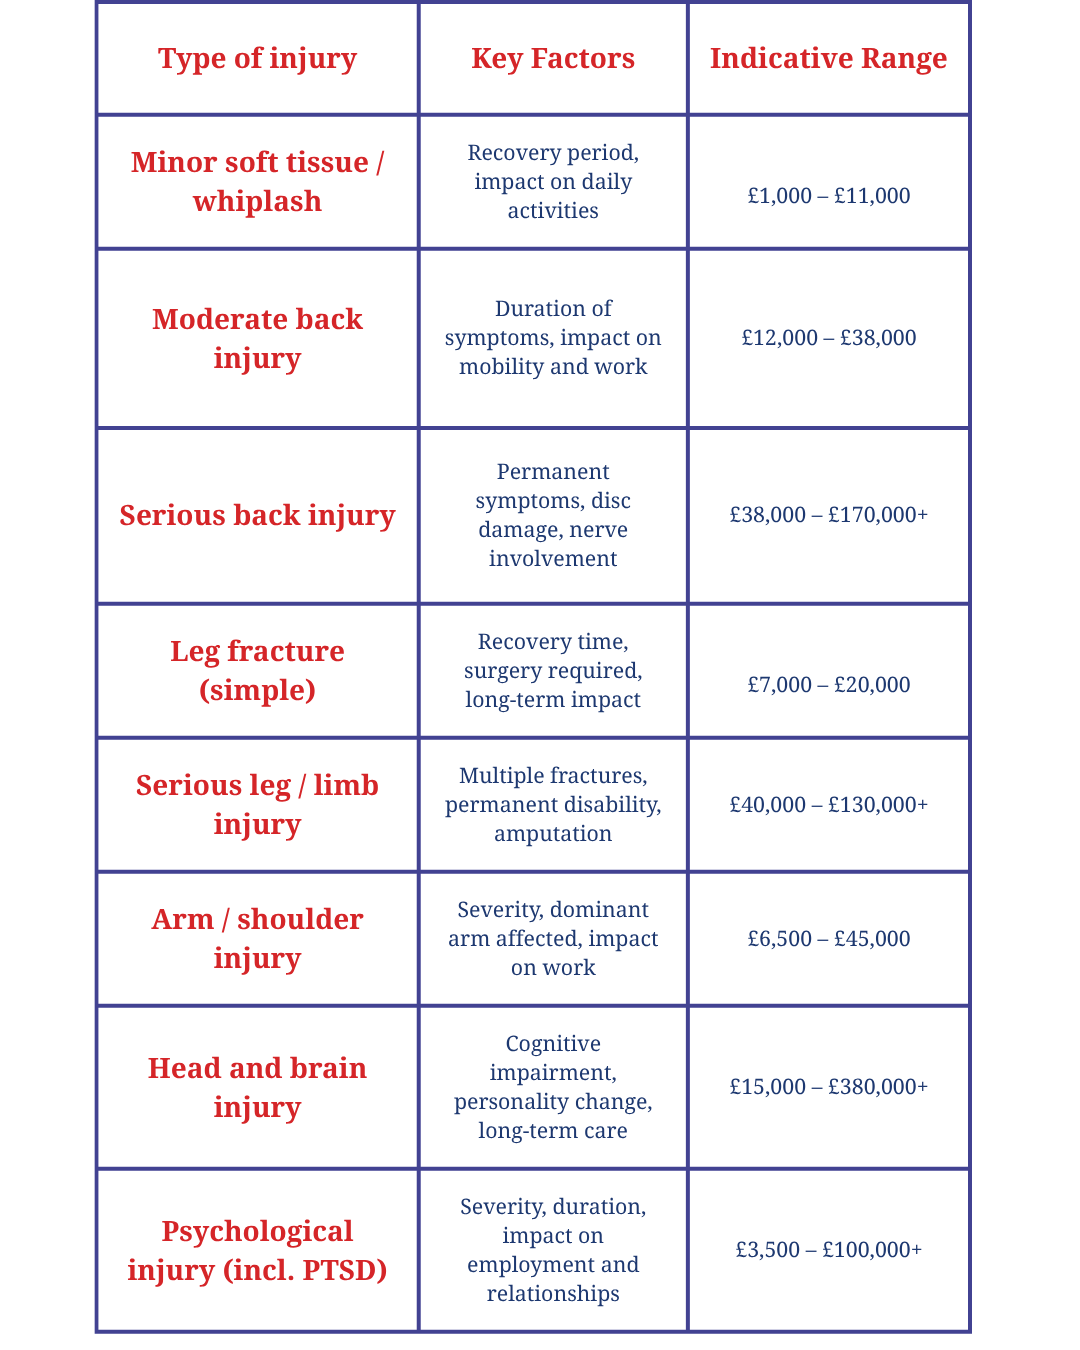
There is no fixed amount. Compensation depends on how serious your injury is, how it affects your daily life and work, and the financial losses you've suffered. Courts and insurers value the injury itself using the Judicial College Guidelines.
These figures cover general damages for the injury only. Lost earnings (past and future), care, travel and treatment costs are calculated separately and added on top. Every claim is different, and these ranges are a guide only, not a prediction of what you will receive.
TYPES OF ACCIDENTS WE HANDLE
SLIP, TRIPS AND FALLS
FALLS FROM HEIGHT
MANUAL HANDLING AND LIFTING INJURIES
MACHINERY AND EQUIPMENT ACCIDENTS
SLIP, TRIPS AND FALLS
FALLS FROM HEIGHT
FORKLIFT AND WORKPLACE VEHICLE ACCIDENTS
LACK OF PROTECTIVE EQUIPMENT
INJURIES CAUSED BY A COLLEAGUE
SERIOUS WORKPLACE INJURIES
CONTACT US TO FIND OUT IF YOU HAVE A VALID CLAIM
HOW DO I MAKE AN ACCIDENT AT WORK CLAIM?
— FREE INITIAL ASSESSMENT
You tell us what happened. We explain whether you're likely to have a claim and how it would be funded. There's no obligation to go ahead.
— GATHERING EVIDENCE
If you go ahead, we gather the evidence: accident book entries, witness statements, photos, training and maintenance records, and your medical records.
— NOTIFY EMPLOYER’S INSURER
We formally notify your employer's insurer of the claim and ask them to respond on liability. You don't need to deal with your employer or the insurer yourself.
— MEDICAL ASSESSMENT
You'll usually be seen by an independent medical expert, who reports on your injury and recovery. Where appropriate, we'll ask the insurer to fund rehabilitation such as physiotherapy.
— NEGOTIATION & SETTLEMENT
We calculate the full value of your claim, including financial losses, and negotiate a settlement. Most claims settle without going to court, although court proceedings are sometimes needed.
— WHAT DOES NO WIN, NO FEE MEAN?
No Win, No Fee means you don't pay our legal fees if your claim is unsuccessful. It is set out in a Conditional Fee Agreement (CFA), which we explain to you in full before you agree to anything.
If your claim succeeds: Most of our costs are paid by your employer's insurer. A success fee is deducted from your compensation, and in personal injury claims this is capped by law at 25% of your damages for pain, suffering and past losses. [VERIFY against firm's CFA terms]
If your claim doesn't succeed: You don't pay our fees. [VERIFY: position on disbursements]
After the Event (ATE) insurance: Where appropriate, this covers certain costs such as expert fees if the claim is lost.
WHY CHOOSE INJURIES DIRECT?
You have a choice about who handles your claim. Here's what you get with us.
A dedicated employer's liability team. Your claim is handled by specialists in workplace injury claims, including an EL/PL solicitor and experienced litigation executives, not general case handlers. Backed by an SRA-regulated law firm. Injuries Direct is a trading style of NJS Law, authorised and regulated by the Solicitors Regulation Authority (SRA No. 8006550). Plain English, no pressure. We explain where you stand honestly, including when we don't think a claim is likely to succeed. Clear about costs from day one. You'll know how your claim is funded and what you may pay before you commit to anything. Rehabilitation, not just compensation. Where appropriate, we push for early access to treatment to help your recovery.
-
Yes, you may still be able to claim. If you were partly responsible, your compensation may be reduced to reflect your share of the blame, but that doesn't necessarily stop a claim.
-
Usually not. Most employers must hold employers' liability insurance by law, and it is normally the insurer that deals with and pays the claim.
-
You may still be able to claim. Other evidence such as medical records, witnesses, photos, messages and emails can help show what happened. Report it in writing as soon as you can.
-
Possibly. Whether you can claim, and against whom, depends on who controlled your work and owed you a duty of care. This could be the agency, the business you were placed with or a site operator. We can look at your situation for free.
-
Yes. Returning to work doesn't stop you from claiming, provided you are within the time limit. You can also claim for time you've already had off.
-
Yes. Receiving sick pay doesn't stop a claim, although any shortfall in your usual earnings can be included as part of your losses.
-
Most accident at work claims settle without a court hearing. Court proceedings are sometimes issued to move a claim forward, but that doesn't mean you'll need to attend a trial.
-
Conditions caused over time, such as industrial deafness, vibration white finger or work-related asthma, can also lead to claims. The time limit usually runs from when you first knew the condition was linked to your work.
-
It depends on the injury and whether your employer's insurer accepts responsibility. Straightforward claims may settle within months. Serious or disputed claims can take longer.